
 Newsletter
 Shop
 Login
 Menü

 Subscribe now


Global uncertainties, rising production and procurement costs, as well as tariffs and trade restrictions, are putting companies in the consumer goods sector under increasing pressure, according to a recent international sentiment and trend barometer from IFH Cologne and Messe Frankfurt. To coincide with the consumer goods trade fairs Ambiente, Christmasworld and Creativeworld, they examined developments in the segments relevant to the fairs in an industry index. For the second round of the survey, 667 representatives from industry, retail and services worldwide were interviewed in June and July 2026.
With an index value of 100.4, up from 100.1 in the first round, the global business climate remains virtually unchanged and, on the whole, subdued. The manufacturing sector appears slightly more confident than respondents from the retail and services sectors. There are also regional differences: Asia is 4.2 index points above the overall index, the Americas 2.3 points above, whilst Europe is 1.2 points below.
“The economy is currently less in a phase of recovery than under pressure to reorient itself. Whilst sentiment is stabilising in some areas, the pressures are shifting from weak demand towards geopolitical uncertainties, rising costs and trade barriers,” said Dr Ralf Deckers, Head of Strategic Insights & Analytics at IFH Cologne.
Costs and crises take centre stage
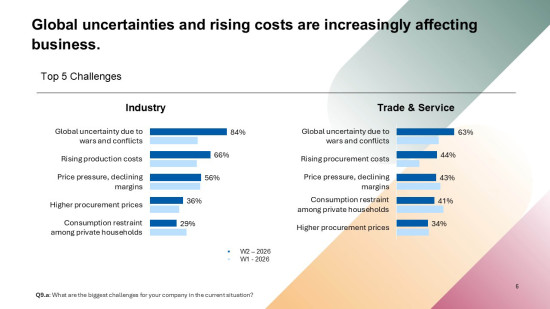
In the manufacturing sector, 84 per cent cite global uncertainty caused by wars and conflicts as the key challenge – compared with 52 per cent in the first wave of the survey. At the same time, rising production costs are gaining in significance: their share has risen from 51 to 66 per cent. Global uncertainty is also on the rise in the trade and services sectors – from 46 to 63 per cent.
Market observers emphasise that the military conflicts in the Gulf region and the associated risks to key international trade and energy routes have highlighted just how closely intertwined geopolitical stability, global supply chains and economic planning certainty are. At the same time, procurement costs are rising, whilst consumer reluctance amongst private households is becoming less significant compared with the first wave of the survey.
In the Americas, 74 per cent of respondents state that they are strongly or very strongly affected by tariffs and trade restrictions. In Asia, the figure stands at 66 per cent, and in Europe at 42 per cent. In the first wave of the survey, the figures were 75 per cent in the Americas, 58 per cent in Asia and 33 per cent in Europe. This means the burden is increasing, particularly in Asia and Europe. Despite this trend, the study notes that companies did not feel significantly better prepared for changes to tariffs and import restrictions.
AI adoption faces structural hurdles
Artificial intelligence is currently used primarily for content creation and media-related applications. Its use is already somewhat more advanced in industry than in the retail and service sectors.
According to the second wave of the survey, the greatest challenges in introducing AI lie primarily in a lack of expertise and in integration into existing systems. Budgetary issues, a lack of resources, and data protection and security risks also play a role.
Cautious outlook
Despite these challenges, companies are taking a positive view of the coming months. The manufacturing sector appears more confident than the retail and services sectors. The slight improvement in turnover trends also points to the first signs of recovery, explains Deckers. Overall, however, expectations remain cautious. “Companies are increasingly adapting to the volatile environment, but there is still no sign of a broad-based upturn,” he emphasises.


 Newsletter